Hail and wind claims are where Davis County homeowners get stuck. We document the roof, meet your adjuster on it, and stay with the roofing side from the first photo to the final walkthrough.
Storm claim on your mind? We'll inspect, document, and walk you through it.
Most claim trouble comes down to a few avoidable things. Knowing them is half the reason it helps to have a roofer who documents the damage properly from day one.
A claim stands on evidence. Without clear, dated photos of the damage, a carrier has little to approve, and it's easy to come up short.
Adjusters move fast after a big storm and don't always get on every slope. Real damage that isn't pointed out can go unrecorded.
An estimate that skips code-required items, or the ice-and-water shield Utah winters call for, leaves the repair and your claim incomplete.
Policies set a window for reporting storm damage, and damage that sat through a winter is harder to tie to one storm. Report it, then document it.
None of this means the system is against you. It means the details matter, and that's the part we take off your plate.
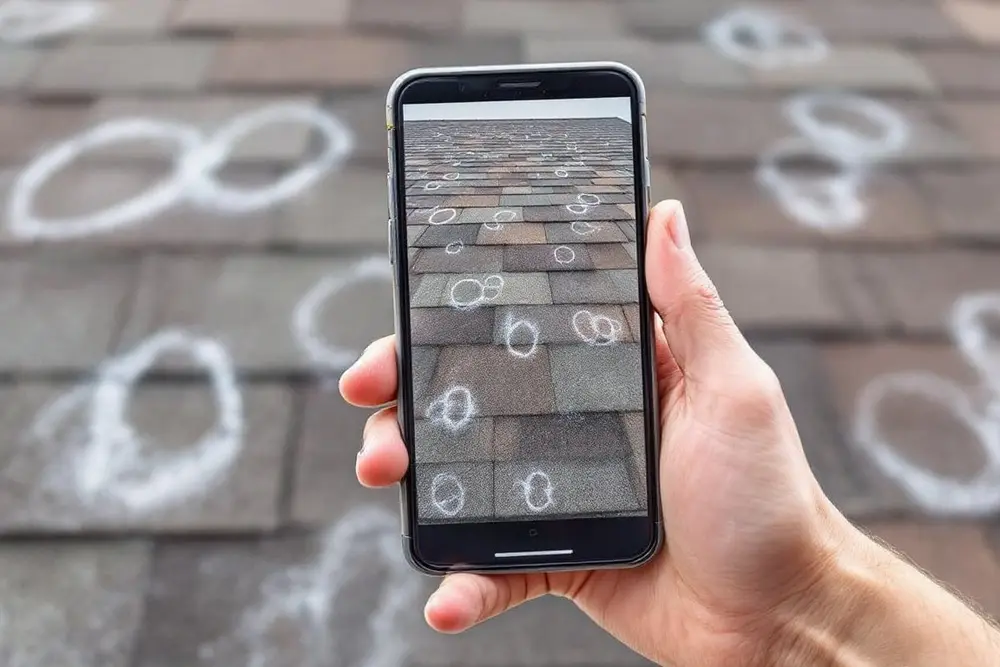
A strong claim starts with a thorough inspection. We get on the roof and go over it in detail, shingles, flashing, vents, gutters, and photograph every area of damage so there's a clear, organized record to build the claim on.
The goal is simple: nothing that should be in the claim gets left out. When the documentation is complete from the start, the whole process goes smoother.
Shingle lines get discontinued. Manufacturers retire colors, change blends, and stop producing profiles entirely, and a roof put on twelve years ago is quite likely wearing something nobody sells today.
It matters because a partial repair assumes there is something to repair it with. If your shingle has been discontinued, patching a damaged slope means putting a different shingle next to the old one. It doesn't blend, and on a roof that faces the street it doesn't blend conspicuously.
So we check. Part of every storm inspection is identifying what is actually on your roof, the manufacturer, the line, the color, and finding out whether it's still available. We photograph it and put that on the record with everything else, so the question of how far a repair has to extend gets asked before the claim is settled, not halfway through the work.
We're roofers, not public adjusters. We don't negotiate your claim for you or interpret your policy, and if you have a coverage question we'll send you to your agent or the Utah Insurance Department. We document the roof properly, meet your adjuster on it, and give you our written scope in the format your carrier works from.
You don't have to climb up and point out the damage yourself. We're on the roof with the adjuster, showing them what we documented and answering the roofing questions as they come up.
When your insurance company sends an adjuster out, we're there, on the roof with them, not waiting in the driveway.
We go over every area of documented damage with the adjuster so the real, complete extent of it is on the record, not just what's easy to see.
We put the full, proper repair in writing, including the code-required items a quick pass can miss. If hidden damage turns up mid-job, we document the supplement instead of surprising you.
You'll know where things stand at each step. No guessing, no chasing.
Every claim is different, but the general shape is usually the same. Once a claim is approved, you're responsible for your deductible, and the approved scope of work is covered by the claim. Many Utah policies now carry a separate wind and hail deductible, often a percentage of the home's insured value rather than a flat amount; it's worth knowing yours before a storm, not after.
What we won't do is guess at your specific numbers or make promises about what your carrier will approve. What we will do is help you understand how your particular claim breaks down, in plain language, so there are no surprises.
One thing we're clear about: every insurance policy is different, and as a roofing contractor we can't advise on your policy's terms. For details on your specific coverage, contact your insurance company or agent. Our job is the roof and its documentation: inspect, document, meet your adjuster, do the work, and provide the completion paperwork. We walk the details with you before any work begins.
"I’ve worked around a lot of contractors over the years, and it’s rare to find a roofing company that actually does what they say they’re going to do. These guys are dialed in. Communication was solid from start to finish, the crew showed up on time, and the job site was clean every single day. No shortcuts, no surprises, and no runaround. What stood out the most was how thorough they were—everything from the inspection to the final walkthrough felt professional and intentional. You can tell they take pride in their work and actually care about doing the job right. If you’re looking for a roofing company you can trust without having to babysit the project, this is the one. I’d recommend them to anyone without hesitation."
"The work was clearly spelled out in the estimate, and the crew was detail-oriented, worked quickly, and cleaned up every last bit of debris."
No. File when there's real damage; a free inspection tells you whether there is. Filing for damage that doesn't exist wastes a claim and can affect your rates.
What hail damage looks like →You do. It's your policy. We give you the photos and the scope so the damage is described accurately, and we'll walk you through the call if you want.
Yes, on the roof. Tell us when the adjuster is scheduled and we'll be there to walk the documented damage together.
Many Utah policies carry a separate deductible for wind and hail, sometimes a percentage of the home's insured value rather than a flat amount. Check your declarations page or ask your agent; it changes what you'll pay out of pocket.
No, and be wary of anyone who offers. Your deductible is your share under the policy. A contractor who 'covers' it is proposing that the claim be misrepresented to your insurer.
We'll tell you whether the roof needs work regardless, and what that looks like out of pocket. If the denial doesn't match what we documented, we'll make sure you have the full inspection report and photos to give your carrier. We don't argue the claim for you. That part is between you and them.
Worried about a roof claim? We'll get on the roof, document the damage, and walk the whole process with you, so you're not facing the insurance company alone.